When reviewing a financing arrangement, many borrowers focus on the loan amount, interest rate and monthly instalment.
But there is another part of the structure that is equally important:
Who is the Borrower? Who is the Mortgagor? And who is the Guarantor?
These three roles can sometimes be held by the same person, but they do not mean the same thing.
Understanding the difference between a Borrower Mortgagor Guarantor structure is important because each role carries a different legal and financial responsibility.
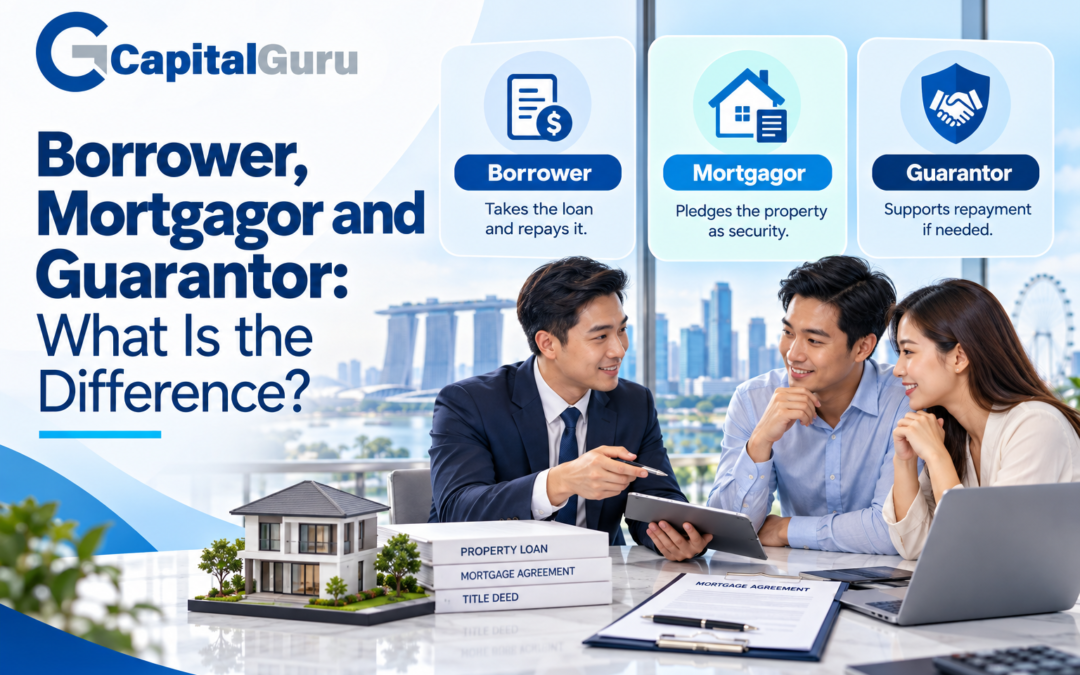
A simple way to remember it is:
Borrower = owes the money
Mortgagor = pledges the property
Guarantor = guarantees the repayment
What Is a Borrower?
The Borrower is the person or company that takes the loan from the lender.
The borrower is primarily responsible for repaying the debt according to the terms of the facility.
This generally includes:
- Principal repayment
- Interest
- Fees and charges
- Late payment charges
- Other amounts due under the loan documents
In a straightforward residential property loan, the property owner and borrower are often the same person.
For example, a homeowner buys a private property in his own name and borrows S$1 million from a bank.
He is both:
The Borrower, because he owes the bank money.
and
The Mortgagor, because his property is being pledged as security.
However, the two roles can also be separated.
What Is a Mortgagor?
The Mortgagor is the owner of the property that is pledged to the lender as security for the loan.
The mortgagor gives the lender a mortgage over the property.
If the loan is not repaid according to the agreed terms, the lender may have rights to enforce against the mortgaged property, subject to the loan documents and applicable law.
The important distinction is:
The mortgagor provides the asset. The borrower owes the debt.
They may be the same party, but they do not have to be.
Example: The Borrower and Mortgagor Are Different
Consider a family-owned company.
Company A needs financing for its business.
The shareholder personally owns a commercial property.
The bank may agree to lend money to Company A, provided the shareholder allows his property to be mortgaged as security.
In that structure:
Borrower: Company A
Mortgagor: Shareholder/property owner
The company owes the money.
The shareholder’s property secures the loan.
The shareholder may or may not also be required to provide a personal guarantee.
If he does, he can effectively perform two roles:
Mortgagor + Guarantor
while the company remains the Borrower.
What Is a Guarantor?
A Guarantor provides a contractual promise to the lender in support of the borrower’s obligations.
If the borrower fails to repay the facility, the lender may seek recovery from the guarantor according to the terms of the guarantee.
This is particularly common in SME financing.
For example, a bank lends S$500,000 to a company.
The company is the Borrower.
The directors or shareholders may be required to provide personal guarantees.
In that case:
Borrower: Company
Guarantors: Directors or shareholders
The guarantors may not receive the loan proceeds personally, but they can still take on significant financial liability.
This is why signing a guarantee should never be treated as a mere administrative formality.
Borrower, Mortgagor and Guarantor Can Be the Same Person
In some financing arrangements, one individual can effectively perform all three roles.
For example, John buys a private property and takes a mortgage loan from the bank.
He owns the property and is responsible for repaying the debt.
Depending on the financing structure and documentation, he may also provide additional personal obligations to the lender.
The structure could therefore involve:
Borrower: John
Mortgagor: John
Guarantor: John
The exact documentation will depend on the lender and facility structure.
Borrower, Mortgagor and Guarantor Can Also Be Different Parties
The distinction becomes more important when the roles are separated.
For example:
Company A takes a loan.
Mr Tan owns a property that is pledged to secure the loan.
Mrs Tan provides a personal guarantee.
The structure becomes:
| Role | Party |
|---|---|
| Borrower | Company A |
| Mortgagor | Mr Tan |
| Guarantor | Mrs Tan |
All three parties are involved in the same financing arrangement, but their responsibilities are different.
This is why the right question is not simply:
“Whose name is on the loan?”
The better question is:
“What role is each party actually signing for?”
What Happens If the Borrower Does Not Repay?
If the borrower defaults, the consequences depend on the financing documents.
The lender may potentially pursue different sources of recovery.
The Borrower
The borrower remains primarily liable for the outstanding debt.
The lender may seek repayment from the borrower and take enforcement action according to the terms of the facility.
The Mortgagor
If the property has been mortgaged as security, the lender may have rights to enforce against that property.
The mortgagor therefore puts the property at risk even if the mortgagor did not personally receive the loan proceeds.
The Guarantor
Depending on the guarantee terms, the lender may also seek repayment from the guarantor.
This is why the financial exposure can extend beyond the original borrower.
Why These Roles Matter
The key point is that Borrower, Mortgagor and Guarantor are three different legal and financial roles.
The borrower owes the debt.
The mortgagor provides the property as security.
The guarantor supports the borrower’s repayment obligations.
Sometimes one person may perform all three roles.
In other cases, different individuals or companies may take on each role.
That is why it is important to understand not just who is signing, but what they are signing as.
Coming in Part 2
The distinction between Borrower and Mortgagor becomes particularly important in residential property financing.
This can arise in situations such as:
- Decoupling
- Two Mortgagors with only One Borrower
- Refinancing after a change in ownership structure
A property can potentially have two legal owners while only one person is the borrower.
However, lenders will generally still want all property owners to pledge their interests as mortgagors so that the lender has security over the entire property rather than only a fractional share.
In Part 2, we will explain how the 2 Mortgagor 1 Borrower structure works, how it interacts with decoupling, and why lenders generally prefer the whole property to be mortgaged rather than relying on a fractional mortgage.
The CapitalGuru View
In financing, responsibility does not always follow the money.
A person may receive no loan proceeds and still take on significant risk through a mortgage or guarantee.
A simple way to remember the structure is:
The Borrower owes.
The Mortgagor pledges.
The Guarantor guarantees.
At CapitalGuru, we believe financing should be understood from both a pricing and structural perspective.
Knowing who carries which obligation is an important part of making an informed financing decision.
This article is for general informational purposes and does not constitute legal advice. The rights and liabilities of borrowers, mortgagors and guarantors depend on the actual financing, mortgage and guarantee documents.