Many SME owners looking for short-term working capital may come across CIMB FlexiPay, a financing facility designed around daily business revenue collection.
Unlike a traditional term loan with fixed monthly instalments, CIMB FlexiPay works more like a revolving working capital facility where repayments are deducted daily based on revenue deposited into the business account.
Understanding how this structure works is important before accepting the facility.
What Is CIMB FlexiPay?
Based on the facility letter, CIMB FlexiPay is structured as an:
- Working capital financing solution
- Daily repayment mechanism linked to revenue collection
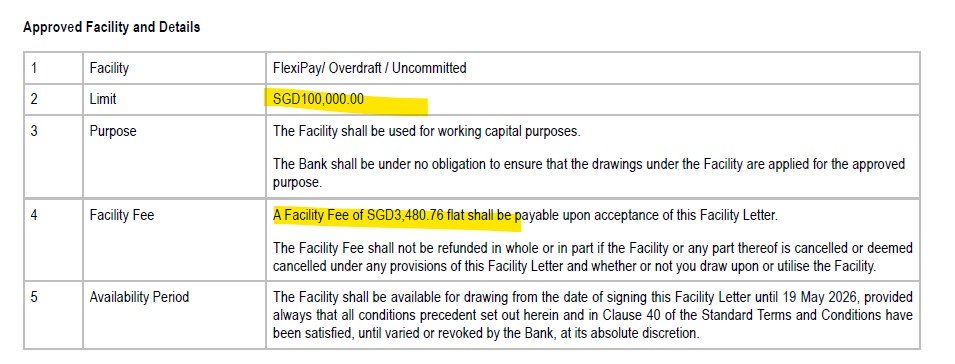
In the above example, the approved limit was:
- SGD100,000 facility limit
The facility also carries:
- Facility fee of SGD3,480.76 upfront
Unlike conventional business term loans, this fee is payable upon acceptance and is generally non-refundable.
How CIMB FlexiPay Repayment Works
One unique feature of CIMB FlexiPay is its repayment structure.
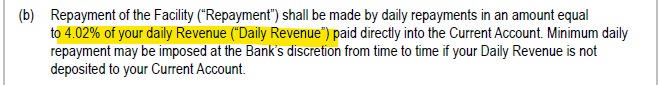
According to the facility terms:
- Daily repayments are linked to business revenue deposited into the CIMB current account
- Repayment amount is based on 4.02% of daily revenue
- The first repayment starts immediately after disbursement
This means repayment fluctuates based on business cashflow instead of fixed monthly instalments.
For businesses with strong daily collections, this structure can help smoothen repayment pressure during slower periods.
Understanding the Loan Tenure
Although structured flexibly, CIMB FlexiPay still has a repayment deadline.
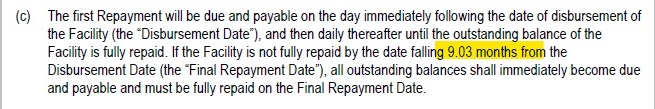
In this case:
- Full repayment is required within approximately 9.03 months from disbursement
If the outstanding balance is not fully repaid by then, the remaining balance becomes immediately due.
This means SMEs must monitor cashflow carefully and avoid over-relying on daily repayment flexibility.
Important Default Conditions
SME owners should also understand the default clauses under CIMB FlexiPay.

Under the facility terms, repayments are linked directly to daily revenue deposited into the CIMB current account. However, if there are insufficient daily revenue credited into the account to meet repayment obligations for 5 consecutive calendar days, it may trigger an event of default
This means businesses with inconsistent daily cashflow or sudden revenue disruption may face repayment risk even though the structure is revenue-based.
The facility is also:
- Uncommitted
- Callable at the bank’s discretion
This means the bank reserves the right to revise, reduce, or cancel the facility if risk conditions change.
Who Is CIMB FlexiPay Suitable For?
CIMB FlexiPay may suit businesses that:
- Have strong and consistent daily revenue
- Need short-term working capital
- Prefer repayment linked to operational cashflow
However, businesses with volatile revenue should carefully assess whether daily repayment deductions may strain cashflow operations.
Final Thoughts
Before accepting any financing facility, SME owners should understand:
- Repayment structure
- Facility fees
- Default triggers
- Cashflow impact
While CIMB FlexiPay offers flexibility compared to fixed instalment loans, it also requires disciplined cashflow management.
At CapitalGuru, we help SMEs evaluate financing structures carefully to ensure facilities align with operational cashflow and business sustainability.