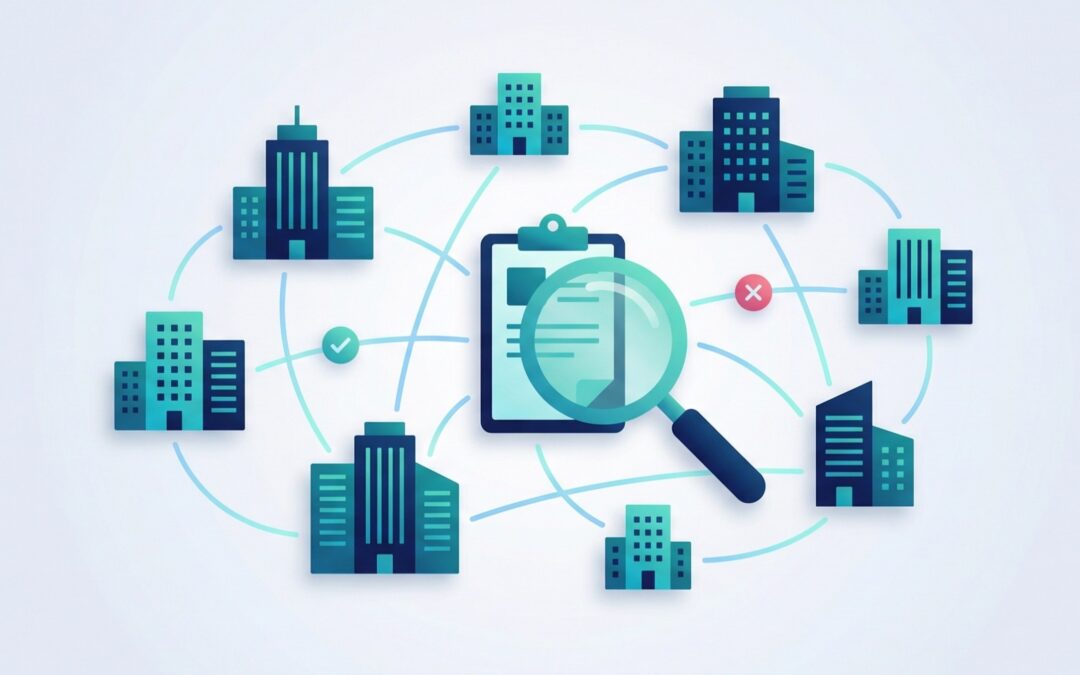
Many SME owners assume that loan approval depends solely on the financial performance of the applicant company. However, lenders often look beyond a single entity. In many cases, related companies can influence how banks assess the overall credit risk of a loan application.
When businesses share common directors, shareholders, or operational links, lenders may evaluate them as part of the same financing ecosystem. As a result, repayment behaviour and financial conduct within related entities can affect the outcome of an SME financing application.
Understanding this lender perspective can help SMEs avoid unexpected delays when applying for business loans.
How Related Companies Are Viewed by Lenders
Banks typically define related companies as businesses that share:
-
Common directors or shareholders
-
Shared operational management
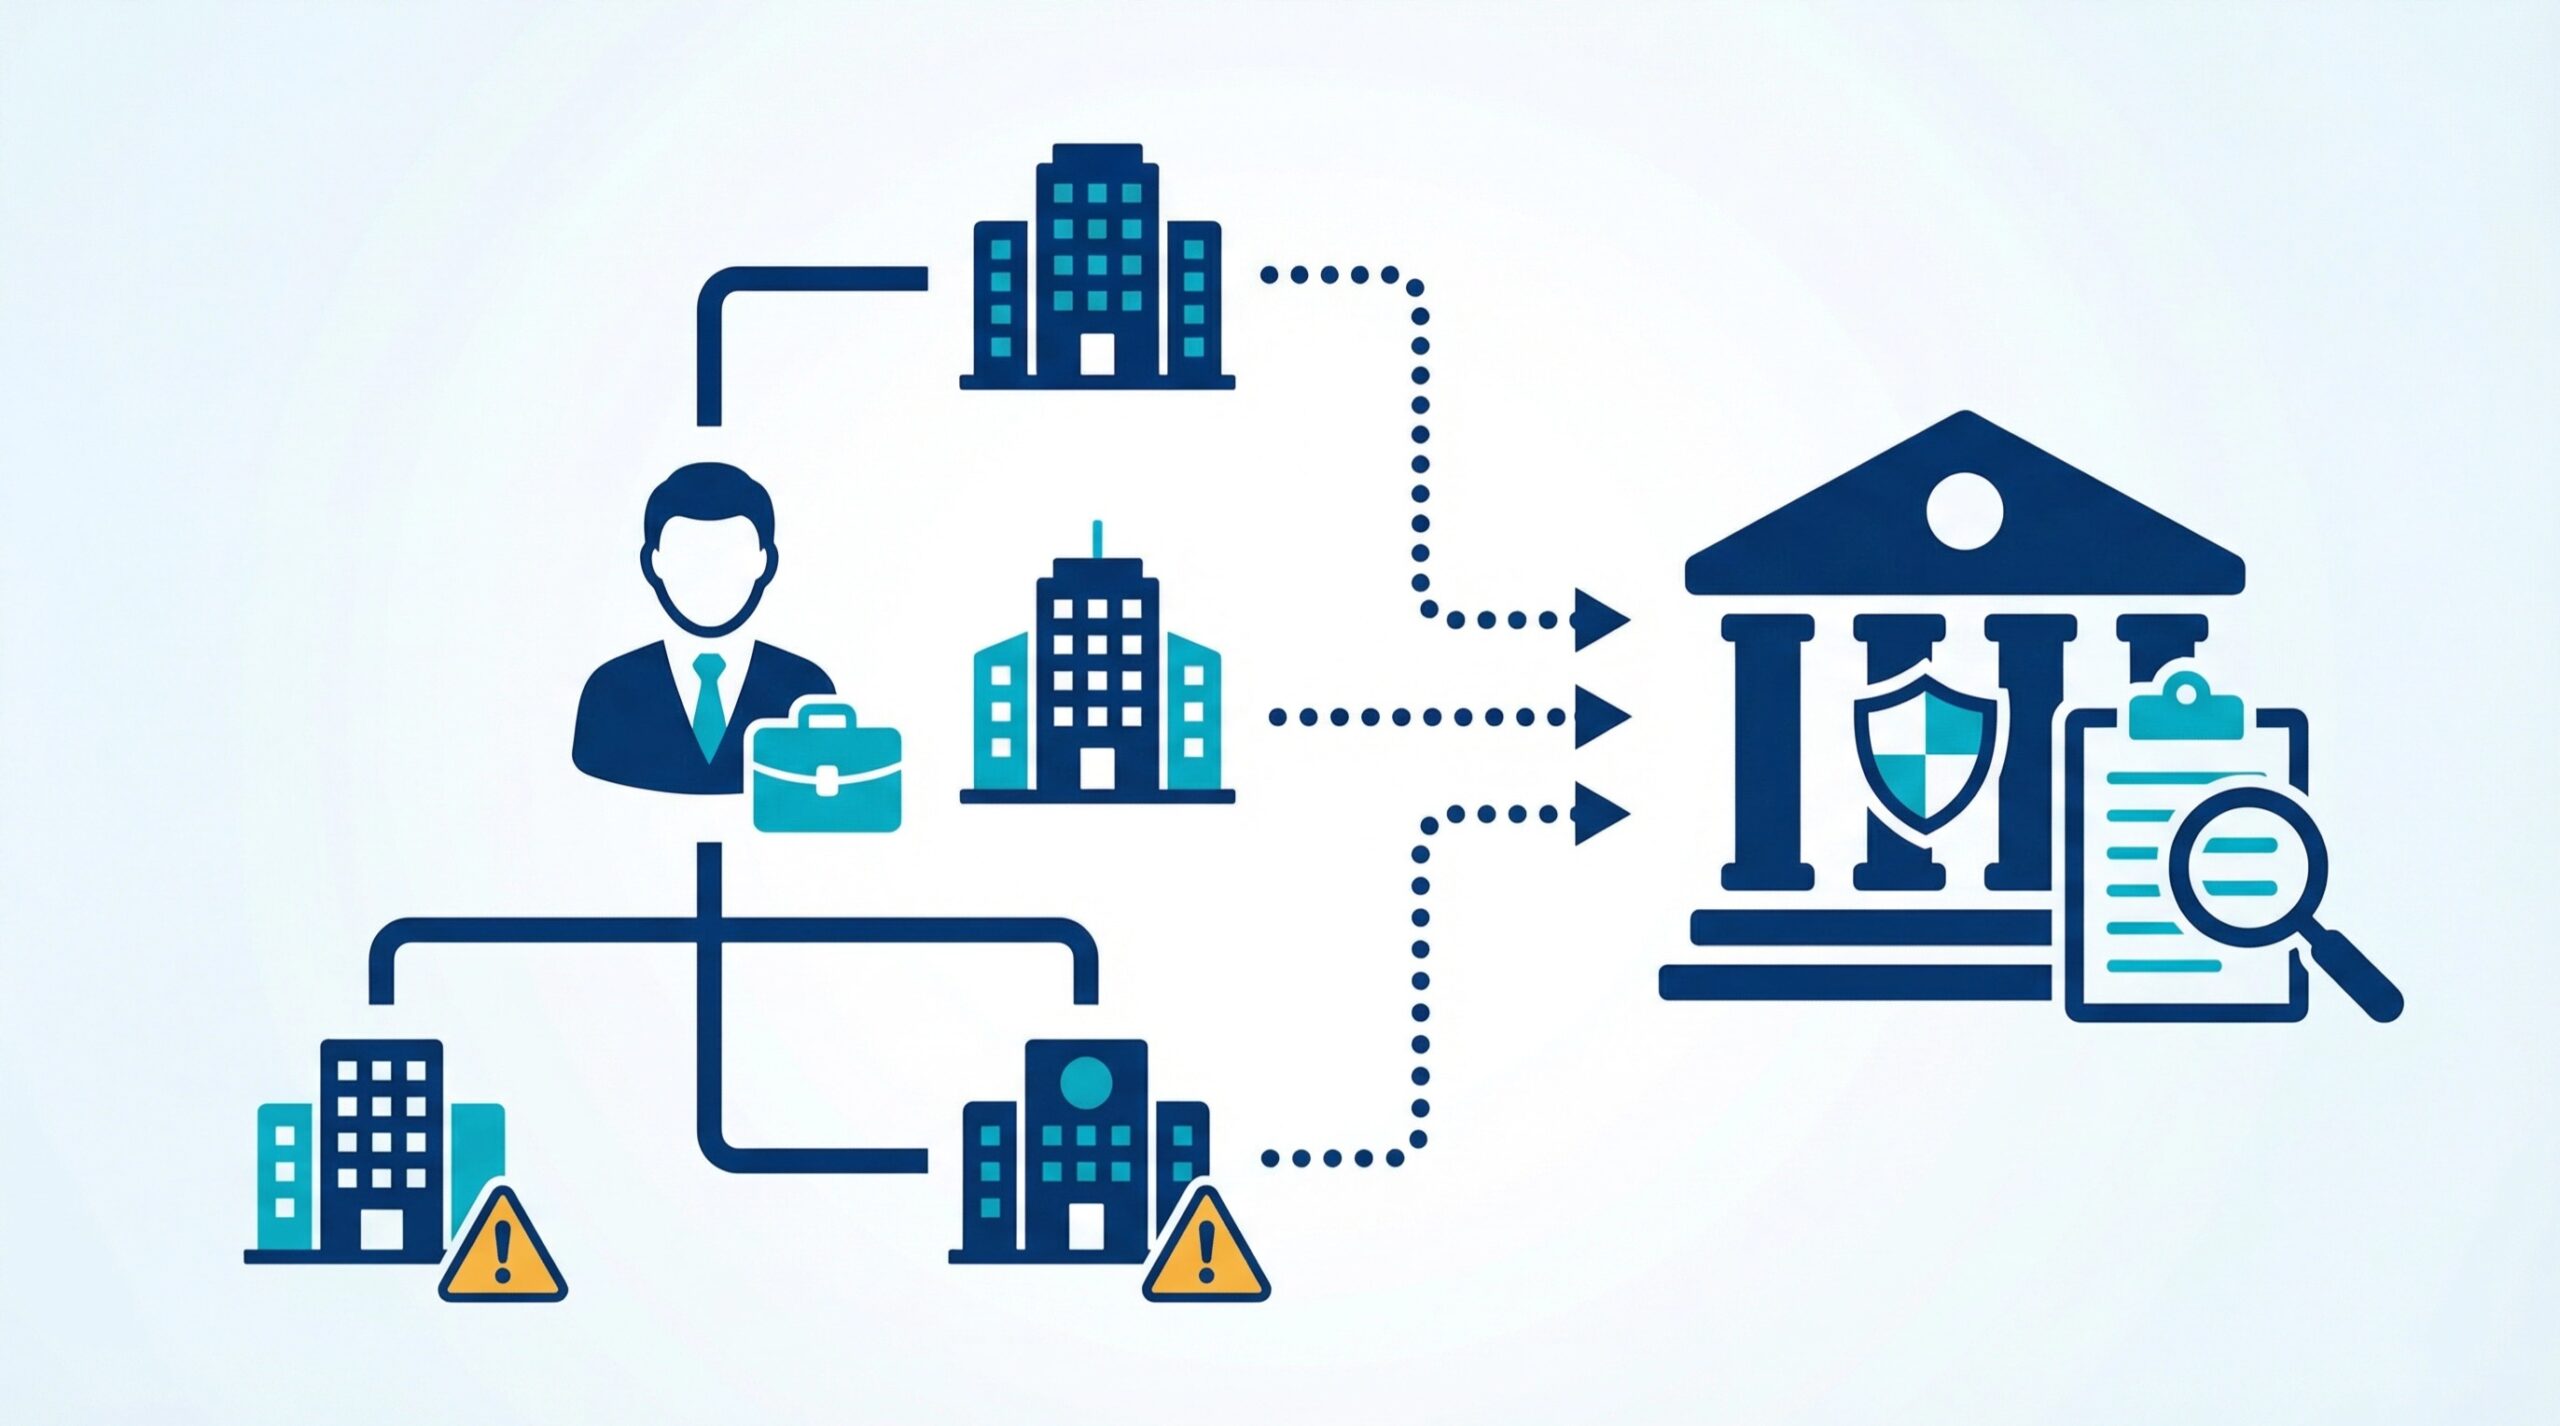
From a lender’s perspective, these connections mean financial risks may not be isolated to one company.
If one of the related entities experiences financial difficulties or poor repayment behaviour, lenders may consider the possibility that similar financial pressures could affect the borrowing entity as well.
Why Payment Conduct of Related Companies Matters
One of the most important factors lenders review is repayment conduct.
Banks often examine how consistently related companies service their financial obligations, such as:
-
Loan repayments
-
Hire purchase instalments
-
Overdraft utilisation
-
Trade financing facilities
If a related company frequently delays repayments or exceeds credit limits, it may raise concerns about financial discipline within the group. Even if the borrowing company has strong financials, issues within the group can slow down the credit assessment process.
 Why Banks Review the Entire Business Group
Credit assessment rarely focuses on a single entity in isolation. Instead, lenders often review the broader financial network connected to the borrower.
This means banks may evaluate:
-
Financial relationships between related entities
-
Cashflow dependencies across entities
-
Shared management decisions that influence financial stability
By reviewing the financial conduct of related companies, lenders can better assess whether risks in one entity could affect the repayment ability of another.
How SMEs Can Manage Risks Across Related Entities
Businesses operating multiple entities should regularly review the financial conduct of related companies, especially before applying for financing.
SME owners can strengthen their credit profile by:
-
Ensuring prompt repayment behaviour across all related entities
-
Avoiding excessive reliance on credit facilities
-
Maintaining transparent financial records between companies
-
Addressing financial issues early within the group
Maintaining strong financial discipline across related companies helps present a healthier overall credit profile to lenders.
Final Thoughts
Many SME owners focus only on the financial performance of the borrowing company when applying for financing. However, lenders often take a broader view that includes the financial conduct of related companies.
Ensuring that all entities under the same ownership maintain strong repayment discipline can significantly improve the chances of smooth loan approval.
At CapitalGuru, we help SMEs assess potential credit concerns early and structure financing applications strategically, reducing the risk that issues within related companies delay the financing process.