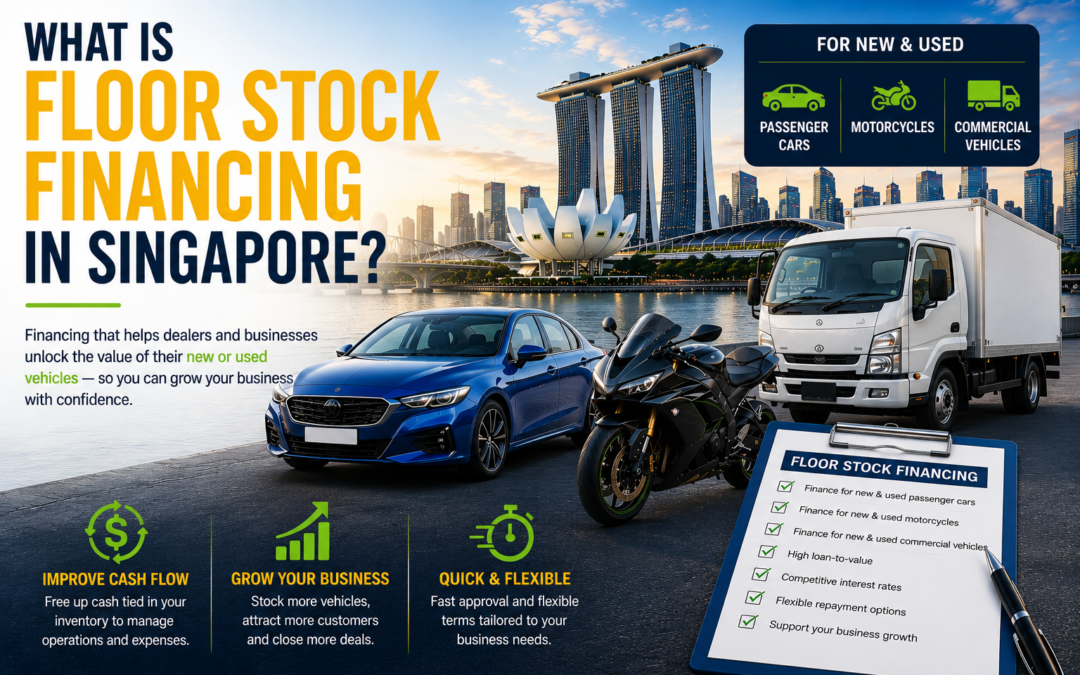
Floor Stock Financing is a specialised financing facility commonly used in the automotive retail industry. In Singapore, it is predominantly used by vehicle dealers who maintain physical inventory for customer viewing and immediate sale.
Many consumers see rows of vehicles displayed in a showroom and assume the dealer owns every unit outright. In reality, a significant portion of that inventory may be financed through Floor Stock Financing.
Without this facility, vehicle dealers would need to commit substantial amounts of shareholder capital simply to maintain inventory. This can limit growth, reduce liquidity, and restrict the dealer’s ability to offer customers a wider selection of vehicles.
Floor Stock Financing solves this problem by allowing dealers to finance inventory while preserving working capital for day-to-day operations and expansion.
What Is Floor Stock Financing?
Floor Stock Financing is a financing facility that allows vehicle dealers to purchase inventory while deferring payment to a lender.
The financed vehicles serve as collateral for the facility.
Rather than paying suppliers entirely out of pocket, the dealer utilises financing to acquire inventory and repays the facility when the vehicle is sold.
In simple terms:
Floor Stock Financing helps vehicle dealers stock more vehicles today and pay for them when they are sold.
The term “Floor Stock” originates from the practice of financing vehicles displayed on a dealer’s showroom floor while awaiting sale.
Who Uses Floor Stock Financing?
In Singapore, Floor Stock Financing is most commonly used by:
- Passenger vehicle dealerships
- Commercial vehicle dealers
- Used vehicle dealers
- Vehicle retailers with physical showrooms
These businesses rely heavily on maintaining inventory to generate sales.
A customer visiting a showroom expects to see multiple models available for viewing and purchase. The larger the inventory selection, the greater the likelihood of securing a sale.
For example:
A car dealer carrying:
- 20 cars
- Average inventory value of $100,000
would require:
$2 million worth of inventory funding.
Without financing, the dealer would need to commit the full $2 million using shareholder capital.
For many dealerships, tying up such a large amount of capital in showroom inventory is neither practical nor efficient.
What Do Floor Stock Financiers Typically Finance?
Examples include:
- New passenger vehicles
- Used passenger vehicles
- Commercial vehicles
- Electric vehicles
The common characteristic is that these vehicles are held as showroom inventory pending sale to retail or commercial customers.
How Floor Stock Financing Works
Step 1: Vehicle Acquisition
The dealer purchases inventory from suppliers, other dealers or from trade-ins
Examples include:
- New cars
- Used cars
- Passenger vehicles
- Commercial vehicles
Step 2: Financing Drawdown
The lender finances the inventory.
Typically, a Floor Stock financier may finance up to 90% of the inventory value, requiring the dealer to contribute the remaining 10%.
The financed vehicles become part of the Floor Stock portfolio.
Step 3: Vehicles Are Displayed for Sale
The vehicles are displayed in the showroom and marketed to customers.
The dealer continues paying financing costs according to the facility terms.
Step 4: Vehicle Is Sold
When a customer purchases a vehicle:
- The financed amount is repaid to the lender
- The dealer retains the profit margin
- The facility limit becomes available again for new inventory purchases
This creates a revolving financing cycle.
Why Floor Stock Financiers Encourage Inventory Turnover
Unlike Trade Financing, which is typically structured around supplier payment terms and trade cycles, Floor Stock Financing is specifically designed to encourage rapid inventory turnover.
In Singapore, Floor Stock Financing interest rates typically range between:
- 0.7% to 0.9% per month for the first 90 days
After the initial 90-day period, financing rates are commonly adjusted upwards by approximately:
- 50 basis points (0.50%)
For example:
A vehicle financed at:
- 0.8% per month
may subsequently incur financing costs of:
- 1.3% per month
if it remains unsold beyond the initial 90-day period.
This pricing structure is intentional.
The floor stock financier wants inventory to move quickly rather than remain parked in the showroom for extended periods.
For example, a vehicle financed at 0.8% per month would incur 2.4% financing cost during the first 90 days. If the vehicle remains unsold beyond the initial financing period and the interest rate increases by 50 basis points, carrying costs can rise significantly.
As a result, successful dealers focus heavily on:
- Inventory ageing
- Days in stock
- Pricing strategy
- Sales conversion rates
From the financier’s perspective, a dealer with fast inventory turnover is generally a lower-risk borrower than a dealer carrying large volumes of ageing inventory.
In many ways, Floor Stock Financing is not just a funding facility—it is also a discipline mechanism that encourages efficient inventory management.
Example of Floor Stock Financing
Consider two car dealerships, each wanting to display 20 cars in their showroom.
Assumptions:
- Average cost per car: $100,000
- Total inventory value: $2 million
- Floor Stock Financing quantum: 90%
- Dealer contribution: 10%
- Floor Stock Financing rate: 0.8% per month
| Dealer A (Own Capital) | Dealer B (Floor Stock Financing) | |
|---|---|---|
| Inventory Displayed | $2,000,000 | $2,000,000 |
| Dealer Capital Utilised | $2,000,000 | $200,000 |
| Financier Funding | $0 | $1,800,000 |
| Monthly Interest Cost | $0 | $14,400 |
| Capital Preserved | $0 | $1,800,000 |
Monthly Interest Calculation
$1,800,000 × 0.8% = $14,400
Although Dealer B incurs a financing cost of $14,400 per month, it preserves $1.8 million of shareholder capital that can be deployed elsewhere in the business.
This capital can be used for:
- Working capital
- Marketing campaigns
- Business expansion
- Additional inventory purchases
- Opening new showroom locations
The facility does not necessarily increase profit margins per vehicle sold. Instead, it significantly improves capital efficiency and return on equity by allowing the dealer to control a much larger inventory base with a relatively small capital contribution.
How Is Floor Stock Financing Different from Trade Financing?
Although both facilities finance inventory, they are designed for different purposes.
| Floor Stock Financing | Trade Financing |
|---|---|
| Vehicle showroom inventory | Supplier purchases and imports |
| Repayment upon vehicle sale | Repayment typically within 90–120 days |
| Secured by vehicles | Secured by trade transactions |
| Designed for vehicle dealers | Designed for importers and distributors |
Trade Financing supports procurement, while Floor Stock Financing supports vehicle inventory displayed for retail sale.
How Is Floor Stock Financing Different from Hire Purchase Credit Lines?
Floor Stock Financing
- Finances inventory held for resale
- Vehicles are intended to be sold as quickly as possible
- Commonly used by vehicle dealers
Hire Purchase Credit Line
- Finances assets intended for long-term ownership
- Commonly used by rental and leasing companies
- Assets generate recurring rental income
Because ownership restrictions exist under hire purchase arrangements, Hire Purchase Credit Lines are generally unsuitable for inventory intended for immediate resale.
We will explore Hire Purchase Credit Lines in greater detail in a future article.
How Is Floor Stock Financing Different from Block Discounting?
Floor Stock Financing and Block Discounting serve completely different purposes.
| Floor Stock Financing | Block Discounting |
|---|---|
| Funds inventory acquisition | Funds receivables |
| Financing before a sale occurs | Financing after a sale occurs |
| Secured by inventory | Secured by receivables |
| Supports stock purchases | Unlocks cash from completed sales |
For example, a dealer may first finance inventory using Floor Stock Financing, sell the vehicles through instalment plans, and subsequently monetise the resulting receivables through Block Discounting.
Read up more on Block Discounting in greater detail in here.
What Do Lenders Look For?
When assessing a Floor Stock Financing application, lenders typically evaluate:
Inventory Turnover
Fast-moving inventory is generally preferred.
Business Track Record
Established dealers with proven sales history are viewed more favourably.
Inventory Management
Strong stock control systems provide greater confidence.
Vehicle Value Stability
Lenders prefer inventory with predictable resale values.
Financial Strength
Profitability, liquidity, and capital adequacy remain important considerations.
Final Thoughts
Floor Stock Financing is one of the most effective tools available to vehicle dealers seeking to expand inventory without committing substantial shareholder capital.
By financing up to 90% of showroom inventory, dealers can preserve liquidity while maintaining a wider vehicle selection for customers.
The facility’s stepped pricing structure also encourages healthy inventory turnover, ensuring that capital continues to circulate efficiently throughout the business.
For vehicle dealerships in Singapore, Floor Stock Financing is not merely a source of funding—it is a strategic tool for growth, scalability, and capital efficiency.